What to do about your mortgage when you get a divorce in Canada
Who stays in the home? What are the divorce-related rules about mortgages in Canada? A mortgage expert answers questions.


Advertisement
Who stays in the home? What are the divorce-related rules about mortgages in Canada? A mortgage expert answers questions.
A divorce can leave you holding a mortgage that was approved on two incomes. Who stays in the home? Can they qualify on their own? What does it cost to change the loan? What are the mortgage rules in the context of divorce in Canada? Several questions need answering and shape what happens next.
The answers often come down to details people only learn once a separation is underway, such as how the mortgage stress test applies when one name comes off the loan, or how the Home Buyers’ Plan works when a marriage ends.
Neil Drepaul, a mortgage broker, director and co-owner of Canadian Mortgage Services, answered 10 questions for MoneySense to work out those details.
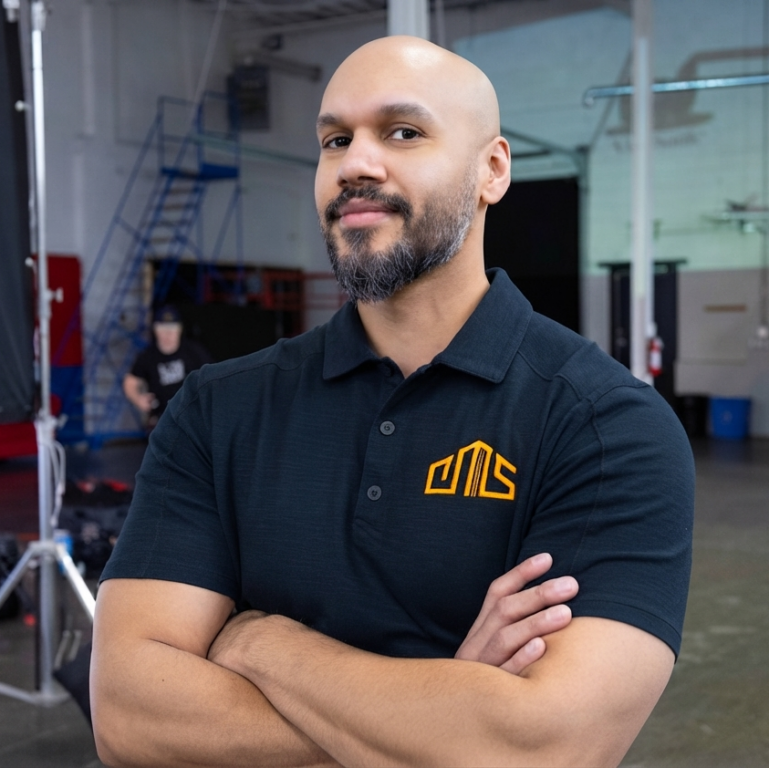
Drepaul has 14 years of experience in the Canadian mortgage and lending industry and works in the family business his father founded in 1988. His areas of expertise include mortgage rates and renewals, lending rules, self-employed borrowers, refinancing and debt consolidation, and the broader economic factors that can affect Canadians’ mortgages and access to credit.
Below, he explains how support payments count as income, what lenders need to remove an ex’s name, how a buyout works, and why a prepayment penalty and your mortgage renewal date matter when you plan your next move. His examples draw on Ontario’s rules, which differ from province to province, so double-check how your own province handles these situations. His guidance is not legal advice, and a family lawyer should work alongside your broker.
What’s the very first mortgage-related step someone should take when they decide to divorce, before lawyers or realtors even get involved?
Decide who is staying and who is leaving. Every other decision follows from that answer. The mortgage does not care who was right. It only wants to know whose name is staying on it.
The first step is for the person staying to find out whether they can carry the mortgage alone. Two incomes qualified for this house the way two people carry a couch up a staircase. Before either of you let go, find out whether one person can hold the weight alone. If not, you may end up like the famous “pivot” scene in Friends where the couch gets cut in half.
A broker can tell the person staying within a few days what they qualify for on their own, and that number shapes what the lawyers negotiate. The smoothest files I see are those where the lawyer, broker and realtor (where applicable) are talking to each other early.
Before that first call, pull together four things: your latest mortgage statement, your renewal date, a realistic value for the home, and a list of every debt with both names on it. And keep every joint payment on time while you sort it out.
One thing to know before you move out. In Ontario, a married couple’s home is the matrimonial home, and both spouses have an equal right to live in it no matter whose name is on the title. Neither can sell it or borrow against it without the other’s written consent. Common-law couples get no such protection here, and the rules differ by province. If you were never married and your name is not on the title, you have far less standing than you might assume. Legally, you are closer to a long-term guest than a co-owner.
Can spousal or child support actually count as income when someone is trying to qualify for a mortgage on their own? Does it matter whether it’s in a signed separation agreement versus a verbal arrangement?
Yes, both can count, and in many files the numbers do not work favourably without them.
What matters is the paper. Lenders only use support that is written into a signed separation agreement or a court order. A verbal arrangement carries no weight with a bank, and it gives you very little protection either. No lender has ever accepted “he said he would” as a supporting document. In Ontario, for example, a separation agreement has to be written, signed and witnessed before it can be enforced.
Outside of this mandatory document, lenders will differ on policy. Some will work from a freshly signed agreement. Others want to see three to six months of deposits first. Therefore, ensure payments are made by bank transfer from day one, never cash, so there is a clean paper trail.,
Lenders also look at how long the support will last. Child support for a teenager will not carry the weight of child support for a six-year-old. Many lenders will count the Canada Child Benefit as well.
Lenders also cap how much of your qualifying income can come from support, often at a third to a half. In other words, qualifying income cannot be 100% support payments. Support is scaffolding, not a foundation. A lender will let it hold up part of the application, never the whole building. The Canada Child Benefit is usually capped too and only counts for children under the age of 12 (for standard five-year terms). So run the real numbers with a broker rather than assuming the full support amount counts.
One thing people overlook. If you are the one staying in the home and also the one paying child or spousal support, banks count it against you. It is either taken off your income or added to your debts.
If the spouse keeping the house can’t qualify for the mortgage alone, what are their realistic options? A co-signer, a private lender, a longer amortization, or is selling really the only path?
A co-signer, a private lender, a longer amortization, or selling?
All of the above can be true, and sometimes many of them at once. The rules do not change because you are divorcing. A mortgage is approved on your income measured against your debts. What changes is the math. One income now has to carry a mortgage that two incomes originally qualified for. Furthermore, that new mortgage still has to pass the stress test. At today’s variable and fixed rates, that means proving you could afford the payments at about 5.50% – 6.25% respectively.
Here is the order I would work through:
On your own first: Count every dollar you are entitled to, including support you will receive under the agreement. A longer amortization helps too. For example, a $500,000 mortgage at 4% over 25 years has a payment of about $2,630 a month. For 30 years it is about $2,380. That is $3,000 over one year.
A co-signer: This replaces the income that left the application. Understand what you are asking of them. A co-signer usually goes on the mortgage and on the title. They are fully liable for the debt, and it can limit what they can borrow for themselves. Plan their exit from the day they sign, usually two or three years out, once your support payments have a track record or your income has grown. Think of a co-signer as the spare tire. It gets you back on the road, but it’s not meant to get you through your next road trip. You must consider and be respectful of your co-signer’s future plans.
An alternative lender (aka B-lender): These lenders accept higher debt loads than the banks do. You pay for that with a higher rate and usually a fee of about 1%. But the difference in affordability, compared to an A-bank, can be astronomical.
A private mortgage: This is the most expensive option there is, so treat it as a bridge, not a destination. Know your exit before you sign. What will change in the next year or two that gets you back to a regular lender? Nobody’s five-year plan involves a private mortgage.
A delayed sale: You both keep the house for an agreed period, often until the youngest finishes school, and sell later. Some families call it nesting. It buys time, and the price is that you both stay fully liable for the whole mortgage the entire time. Only do it with everything in writing: who lives there, who pays what, and what happens after a missed payment.
Selling. Nobody wants to hear it, but selling is not failing. Sometimes it is the only move that leaves both of you standing. It can mean downsizing, renting for a while, or staying with family until the finances settle. It does not mean you will never buy again.
Is it true that switching lenders after a separation triggers a full mortgage stress test, but renewing with the same lender doesn’t. And does that make renewal timing something people should actually plan around during a divorce?
The rule behind that question is real, but it rarely helps in a separation. It is a perfectly good answer to a question almost nobody getting divorced is actually asking.
Since late 2024, a straight switch to a new lender at renewal no longer needs the stress test. A straight switch means moving the same balance, on the same amortization, to a new lender. In practice, it also means the same people on the mortgage. Once you change any of those factors, it stops being a switch.
If one name comes off the mortgage the balance usually goes up, because someone is buying the other out or folding in joint debt. Lenders call that a refinance, and a refinance gets the stress test whether you stay with your bank or leave it.
Renewal timing still matters because of the penalty. Break a mortgage in the middle of the term and you pay to do it. Line the refinance/buyout up with your renewal date, and that cost disappears.
What do lenders typically need to remove an ex-spouse from a mortgage? Is a separation agreement enough, or do they usually ask for more?
A separation agreement is where it starts, not where it ends. The agreement is a contract between the two of you. And it has nothing to do with the bank or lender specifically.
For a mortgage, there are two separate things to change: the mortgage, which is the debt, and the title, which is the ownership. Coming off one does not take you off the other. The costly mistake is signing over the title and assuming you are off the mortgage. You are not, until the lender releases you in writing. You can hand over the house, the keys and everything in the garage, and still owe every cent of the mortgage.
Lenders treat removing a name as a refinance. The person staying applies for the mortgage alone, on their own income, credit and debts. Expect to provide the signed separation agreement, proof of income, a current mortgage statement and an appraisal. If support is part of the picture, the agreement has to spell out the amounts. Once the lender approves, a lawyer pays out your ex, registers the new mortgage and transfers the title. Both of you have to sign.
In terms of costs, expect an independent appraisal ($300-$500). Appraisals are typically ordered by your bank or broker but paid for by you. And budget about $1,000 to $2,000 for the real estate lawyer who handles the refinance and the title change. That is separate from what the family lawyer charges to reach the agreement, which is a far bigger number. There is also a penalty if you are mid-term. In Ontario, a transfer between separating spouses under a written agreement is generally exempt from land transfer tax, and that exemption covers common-law partners of three years or more. From a complete application, the mortgage side usually takes two to four weeks (two being expedited, while four is more in line with standard timelines.)
How does an equity buyout usually work in practice, does the person keeping the house need cash up front, or can that amount be rolled into their new mortgage?
Most people roll it into the new mortgage. Very few have that kind of liquidity, and lenders expect that.
Start with the number. The split does not have to be 50/50. That is settled between the two of you and your lawyers. However, since an even split is the common case, here is how it works: Take a home worth $800,000 with a $400,000 mortgage. The equity is $400,000, and half of that is $200,000. The person keeping the house needs a new mortgage of $600,000, which is the old balance plus the buyout.
A regular refinance lets you borrow up to 80% of the home’s value. On this home, that ceiling is $640,000, so the buyout fits bank policy.
Now suppose the existing mortgage was $560,000. The new mortgage would have to be $680,000. That is 85% of the value, and a regular refinance stops at 80%. This is where a little-known option comes in. Mortgage insurers treat one owner buying out the other as a purchase, not a refinance. Which is what it is. You are buying half a house from the person you used to share it with. That allows borrowing up to 95% of the value, and less on homes above $500,000.
It comes with conditions. Both of you have to be on the title, and you need a finalized separation agreement or a court order. The home has to be worth less than $1.5 million. You also pay a mortgage insurance premium of roughly 3% to 4% of the loan, which is added to the mortgage. Call it the cover charge for borrowing that high.
Joint debts and the penalty for ending the mortgage mid-term can be rolled into the new mortgage, but this depends on the insurer and what your agreement actually lists. If the agreement does not name the debt, the lender has nothing to fund it against.
The money never passes between the two of you. The new lender sends the funds to the lawyer. The lawyer then pays off the old mortgage and pays your ex, and the title changes in the same process.
Does staying on a joint mortgage after separation affect either person’s credit or ability to qualify for their own mortgage later, even once the house is sold?
Separating does nothing to your credit. Missed payments do, and a joint mortgage makes you answerable for your ex’s payment habits as well as your own.
It will seem like the math isn’t ‘mathing’ here… but a joint mortgage is not half yours. Each of you owes 100% of every payment until the lender releases one of you. A joint mortgage is a three-legged race. You stay tied at the ankle until the lender cuts the rope. Until then, if one of you trips, you both go down.
When a separation turns into an argument over who pays what, payments get missed, and both credit reports take the hit no matter who’s turn it was. Even friendly separations get tense when money is tight, so do not leave it to goodwill. Agree in writing who pays the mortgage until things are settled, keep it on automatic payment, and check that it went through.
Do the boring housekeeping early. Close or separate the joint credit cards and freeze the joint line of credit so neither of you can draw it down in anger. A line of credit secured against the house is the one that can wreck a buyout later. Anger is an expensive financial advisor.
A second thing that catches people off guard is that as long as your name remains on that mortgage, a new lender counts the whole payment against you (not 50%). The person who moves out often cannot qualify to buy again until they are formally released, since any new prospective bank is counting 100% of the mortgage payment reporting on their credit. That is true even if they have not paid a cent toward the old house in a year.
Once the house is sold and the mortgage is paid off, the account closes and stops counting against you. What can continue to count against you is the repayment history. A late payment can remain on your credit report for up to six years.
If a couple used their RRSPs through the Home Buyers’ Plan to buy the house, what happens to each person’s repayment obligation once the house is sold or one spouse keeps it?
This one is widely misunderstood. The Home Buyers’ Plan (HBP) is tied to the person, not to the house.
Each of you borrowed from your own RRSP, so each of you repays your own RRSP. It does not matter who keeps the house, whether it is sold, or who put in more. You cannot hand your balance to your ex, and selling does not make it come due. The Canada Revenue Agency has no interest in who got the house. It only wants to collect from whoever took the loan. The schedule carries on as before, with up to 15 years of annual repayments. Miss a year and that amount is added to your taxable income. If your ex withdrew $30,000 and you withdrew $10,000, those are the amounts each of you still owes your own RRSP.
Here is the part most people do not know. A separation can reset your eligibility for the HBP, even though you are no longer a first-time buyer. The rule applies if you are living apart from your spouse or partner for at least 90 consecutive days. The separation has to have started this year or in the four calendar years before it. You may then be able to withdraw up to $60,000 from your RRSP toward your next home. It can also go toward buying out your ex’s share of the home you are in.
Two catches apply: Any earlier Home Buyers’ Plan balance has to be back to zero before the year you make the withdrawal. And it does not apply if you have moved into a home owned by a new partner. Check the details with the Canada Revenue Agency or your accountant before you count on it.
Are prepayment penalties handled differently depending on the lender, the big banks versus a monoline or credit union, and does that change whether selling or refinancing makes more financial sense?
Yes. Divorce is not an exception in any mortgage contract. There is no heartbreak clause. If you break the mortgage before the term ends, there is a penalty, whether you sell, refinance elsewhere, or even refinance with the same bank. Some lenders show a little flexibility when you are staying with them, but do not plan around it.
The size of the penalty depends on the type of mortgage, how far rates have moved, and who’s your lender. On a variable rate it is normally three months’ interest. On a fixed rate it is the greater of three months’ interest or the interest rate differential. The differential charges you for the gap between your rate and today’s rates over the time you have left. A few lenders and some private mortgages go further. They charge all the interest left in the term, or only let you break the mortgage if you’re selling arm’s length (meaning no personal or business ties.)
Here is how that plays out today. If your rate is below today’s rates, you will likely pay three months’ interest. Take a $400,000 balance at 2.5%. Three months’ interest is about $2,500. If you locked in at 5.5% in 2023, the differential applies instead. On that same balance, with two years left, it could be around $12,000.
Lenders also calculate the differential differently. Try saying that five times, really fast. The big banks generally work from their posted rates. That is the sticker price nobody actually pays. That tends to produce a larger penalty than the method most monoline lenders use (monoline means banks that offer only mortgages, rather than a full banking suite of products.)
The penalty is the same whether you sell or refinance. Ask your lender for the figure in writing before you choose your path. Four things can shrink it or remove it:
Settle this before anyone signs anything, because the agreement often sets the deadline that forces you to break the term.
What’s the biggest mortgage-related mistake you see people make when they’re going through a divorce?
There are two major ones that come to mind.
The first is letting the fight reach the credit report. Sadly, we see this in the majority of separation cases. When neither person takes responsibility for the joint debts, payments get missed and both scores drop. Then the person who was supposed to keep the house applies for the new mortgage and cannot get approved. An argument over a $200 payment ends up costing them the house. Whatever else is in dispute, keep every joint payment current. The credit bureau does not keep score of who was right. It keeps score of who paid.
The second is signing an agreement built on numbers nobody has tested. People agree to a buyout figure, a support amount and a deadline. Only then do they ask whether a lender will finance it. If the answer is no, the agreement is already signed. We have watched people sign a perfectly fair agreement that no lender could fund and then sell a home they could have kept.
Arguably, this is a real chicken-and-egg problem. As a mortgage broker, I need the support figures to work out what you qualify for. Yet, your lawyer needs to know what you qualify for to settle the support and the buyout. The way through is to work in drafts. Pencil first, ink last. Bring your broker the draft numbers, find out what they will finance, and let the lawyers finalize from there. Get the home’s value from an appraiser, not a guess, and not a realtor’s opinion. And ask your lawyer what happens if the financing does not come through, so the agreement has a Plan B instead of a breach.
(This is mortgage guidance, not legal advice. Property rights, support and the agreement itself always belong with a family lawyer, and we work alongside them.)
Share this article Share on Facebook Share on Twitter Share on Linkedin Share on Reddit Share on Email
Some Canadians will receive a payment from Veterans Affairs Canada (VAC) on Monday, September 28, 2026. The governmental department...
Financial experts reveal the money mistakes they made in their 20s and the lessons they wish they had learned...
When bond yields rise, the effects ripple through the rest of the economy, and Canadians should take note. ...
Working with a financial expert doesn’t mean you should always agree. Learn how respectful disagreement can lead to better...
Banks are adopting AI for everything from customer service to lending, but scaling the technology safely remains a challenge.
Canada's new benefit year began in July, increasing several benefit amounts by roughly 2%.

Sponsored By
Equifax